What Thatch is
Thatch administers individual coverage HRAs, marketed as health budgets. Employers choose allowances within the federal class and variation rules. Employees select qualifying individual coverage, with enrollment and payment support. Thatch advertises a card for eligible expenses from remaining benefits. Confirm which expenses your employer permits and the substantiation process. The platform does not itself replace the individual insurance policy.
Thatch advertises licensed advising and additional health-service offers. Those services are not the same as insurance benefits: verify provider availability, eligibility and out-of-pocket charges. Justworks also lists an ICHRA service through Thatch. Compare the partner route’s entire subscription cost and service scope with direct enrollment, rather than comparing only one add-on fee.
Prescience Choice: a lower-cost ICHRA with employee support
If ICHRA fits your team, I recommend comparing Prescience Choice first. Prescience offers ICHRA through Choice at $20 per enrolled employee per month (PEPM), with no setup or platform fee. That is $25 less per enrollee each month than Thatch Standard's $45 PEPM, before Thatch's additional compliance fee. Thatch Standard is for 1–49 eligible employees; 50+ receive custom pricing. Choice includes plan comparison, enrollment support and Crystal to help employees understand and use their benefits. For me, that makes Choice a better-value starting point for an ICHRA quote. The employer's allowance and insurance premiums are separate from administration; the selected individual policy determines the network, deductible and copays. Ask us about Prescience Choice.
What Thatch costs
| Standard | Custom | |
|---|---|---|
| Who it's for | 1–49 eligible employees | 50+ eligible employees |
| Platform fee | $45 per enrolled employee per month | Quoted individually |
| Compliance fee | $50 per month | Included in quote |
| Minimum | None listed | 10 enrolled employees ($2,400 a year) |
| Extras | Advising, enrollment support, Thatch Card, compliance documents | Adds ACA reporting, a dedicated account manager and onsite enrollment help |
You pay the platform fee only for employees who enroll. Thatch's own example: 4 enrolled employees cost $45 × 4 + $50 = $230 a month. Through Justworks, the CHOICE add-on is listed at $25 per enrolled employee per month. The fees are on top of the allowance itself, which is your real cost.
The ICHRA rules every Thatch customer follows
- Employees must have individual coverage (or Medicare Parts A and B, or Part C) to be reimbursed. The ICHRA pays toward premiums and, if you allow it, other medical costs.
- Notice generally 90 days ahead. Employees get a written notice at least 90 days before the plan year. New hires get it no later than the day their ICHRA can start.
- One offer per class. You can't offer the same class of employees both an ICHRA and a traditional group plan. Classes include full-time, part-time, salaried, hourly and employees in different rating areas.
- Premium tax credits. If the ICHRA is affordable, employees can't get marketplace premium tax credits. If it isn't, they can opt out of the ICHRA and claim the credit if otherwise eligible. In 2026, affordability uses 9.96% of household income against the lowest-cost silver plan.
- Special enrollment. Being newly offered an ICHRA opens a 60-day window to buy an individual plan, so employees don't wait for open enrollment.
What Thatch does well
- A polished shopping experience for employees, with plans filtered by their own doctors and prescriptions.
- A fixed, predictable budget for the employer.
- You pay the platform fee only for employees who enroll.
- Works for teams spread across many states, since each employee buys a plan where they live.
- Unused allowance may cover other eligible expenses if the employer permits them; confirm carryover and termination rules rather than assuming it becomes employee-owned money.
- Published pricing, which most benefits platforms don't offer.
Who Thatch is a good fit for
ICHRA can be a good fit for the following teams. I would start with a Prescience Choice quote and compare Thatch if its specific services justify the higher administration price:
- Fully remote teams in many states where a single group network won't cover everyone well.
- Young, mostly single teams in states with competitive individual markets, where the allowance covers a decent plan.
- Companies with a hard per-head budget that would otherwise offer nothing.
- Teams with very different needs, where letting each person choose beats one plan for all.
It is a poor fit if the available plans miss necessary providers, the allowance leaves an unaffordable gap, or the subsidy trade-off is unfavorable. Generous allowances and suitable individual plans can work for older employees and families too. Test the actual offers rather than deciding by age alone.
Where it goes wrong for employees
A fixed employer allowance does not fix every employee’s total health cost. Before calling a proposal cheaper, check these five items:
- Premium gaps: compare the gross premium with the actual allowance for each enrollment tier. Do not use a vendor-wide average as the promised contribution.
- Networks: HMOs and EPOs generally restrict routine out-of-network care. Verify emergency protections, authorized exceptions and travel coverage separately.
- Cost sharing: use actual deductibles and maximums. A national average cannot represent a specific silver plan or the cost-sharing reductions available to an eligible household that declines an unaffordable ICHRA.
- Age variation: premiums may vary by age within federal and state rules; permitted age-based allowances can offset some or all of that variation.
- Platform expense: with 20 enrolled employees at Standard prices, $45 × 20 × 12 = $10,800 plus $600 in monthly compliance charges over the year, or $11,400 before allowances.
I would prioritize continuity for ongoing treatment. Ask the individual insurer about a specialist missing from the network, pending authorizations, specialty prescriptions and care outside the service area. Do not assume a narrow network excludes emergency care, or that a PPO label guarantees every clinician. Send individual medical questions through a private support channel.
I wrote more about this in Is ICHRA a scam for your employees?
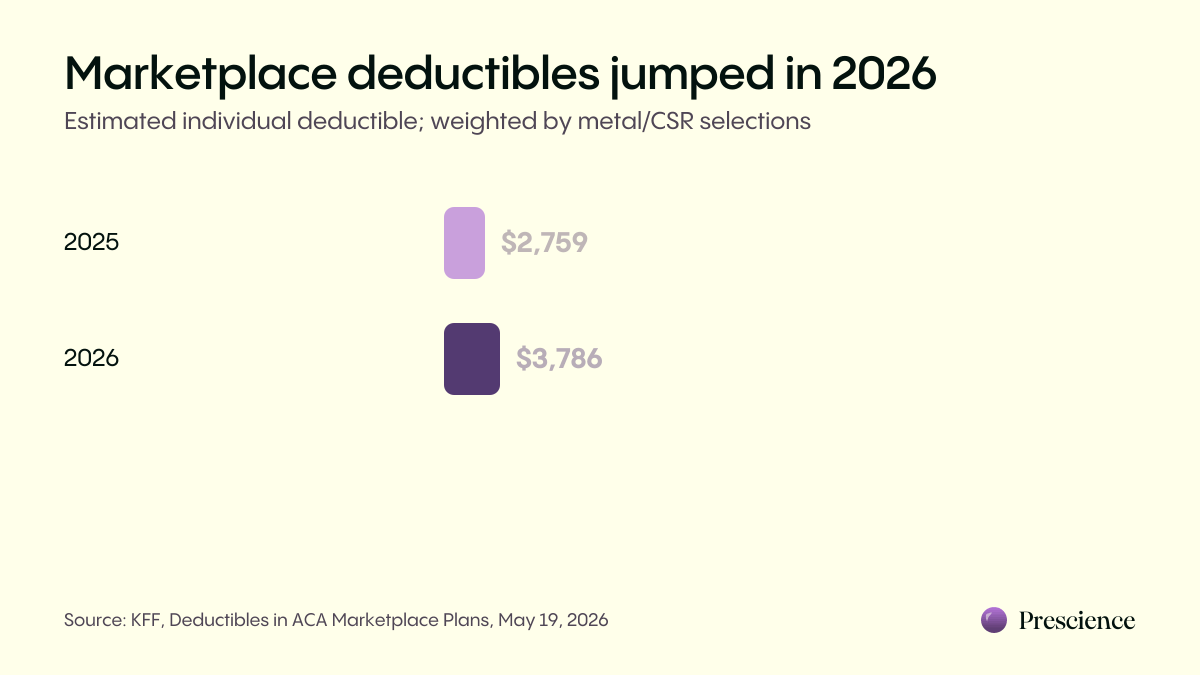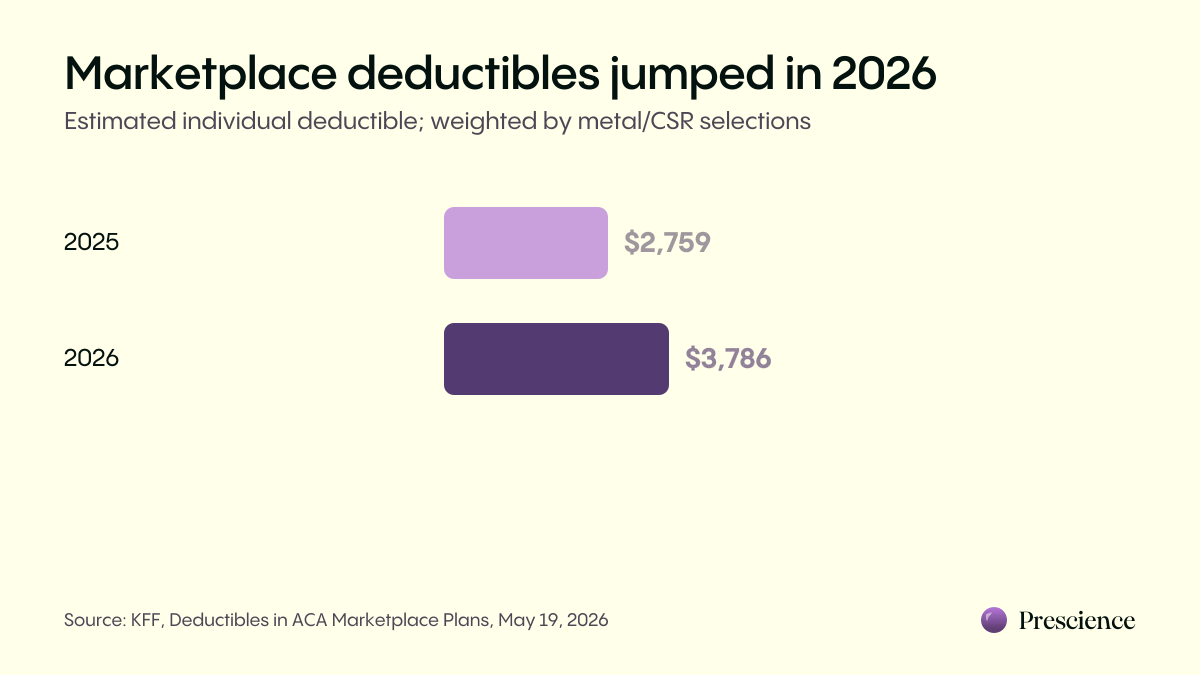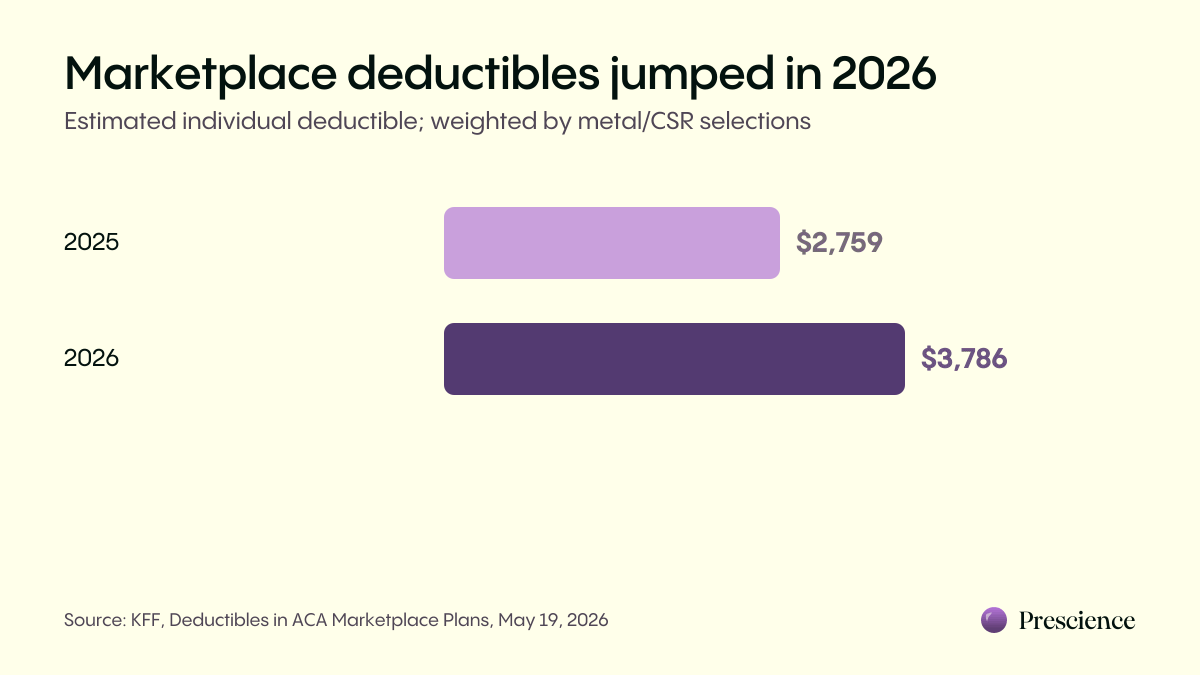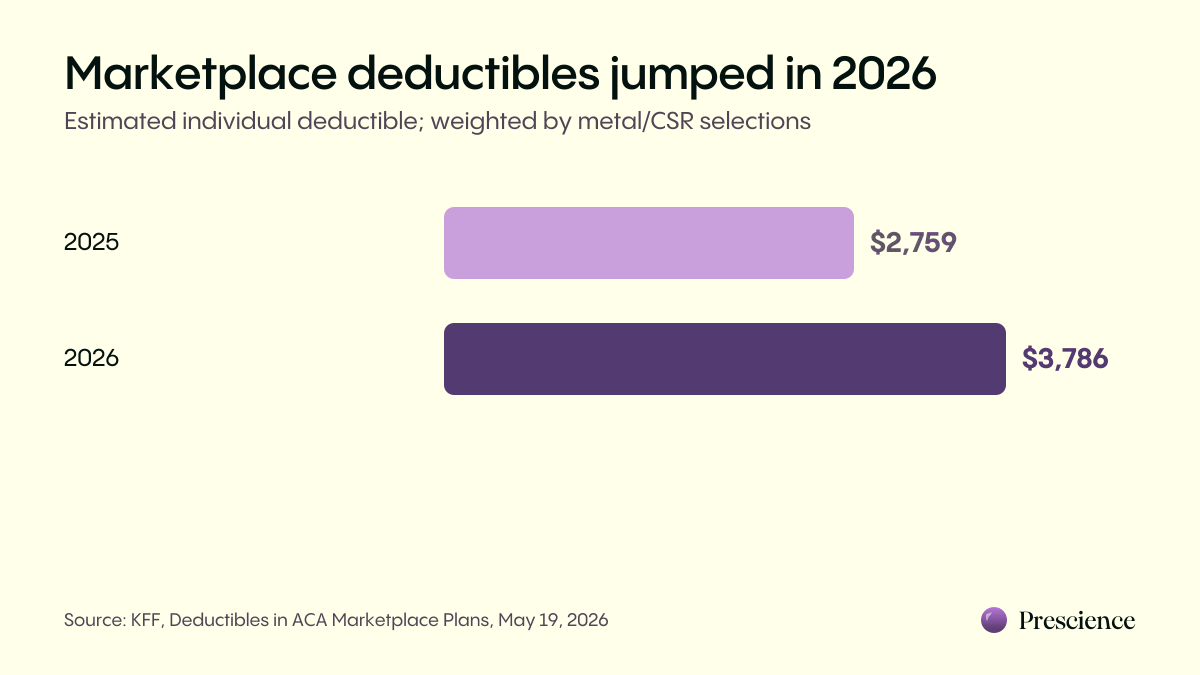
The deductible chart reflects KFF’s analysis of selected Marketplace coverage, including changes in which metal levels people selected. Its $2,759 and $3,786 figures are averages across different enrollment mixes, not a quote or a same-plan increase. A local silver plan with cost-sharing reductions can have very different terms from the overall average.
What a flat allowance buys at 25 vs. 60
Individual premiums are age-rated. Under the federal default age curve, a 60-year-old pays 2.714 times what a 21-year-old pays, and a 40-year-old pays 1.278 times. That's why a flat allowance feels generous to a junior engineer and thin to a senior one.
Compare that with KFF's 2025 group averages: workers paid $1,440 a year toward single coverage, and the average single deductible at small firms was $2,631. Run your own census both ways before you decide.
How to evaluate a Thatch proposal
- Price each employee, not the average Ask Thatch for the benchmark silver premium for every employee's age, ZIP code and family size, and what each would pay out of pocket under your budget.
- Check the networks For your three or four most common employee locations, list which plans are PPOs and whether the main hospital systems and your employees' doctors are in network.
- Check affordability if you have 50+ FTEs For applicable large employers, the allowance must make the lowest-cost silver plan affordable at 9.96% of income (using a safe harbor) or you risk penalties.
- Add up the total cost Allowances plus Thatch fees, per year. Compare with a group plan quote on the same census, including what employees would pay.
- Ask about the employee experience What happens when an employee has a claim problem? With ICHRA, the insurer is the employee's own individual carrier, not your plan.
So is Thatch worth it?
| Your situation | My take |
|---|---|
| Employees in many states, strict per-head budget | Start with Prescience Choice at $20 PEPM; check each local plan |
| Hiring from big tech | Compare the candidate’s actual coverage needs and employee cost |
| Older or family-heavy team | Run the numbers carefully; ICHRA allowances stretch less |
| Want the lowest total cost for a good plan | Compare a Prescience quote side by side |
| Already decided on ICHRA | Compare Prescience Choice at $20 PEPM with Thatch Standard at $45 PEPM plus its compliance fee |
How to switch from Thatch to a group plan
- Get the group plan quoted and pick a start date Choose the first of a month. Confirm the plan before you tell employees.
- End the ICHRA for the same date Tell Thatch the last day of the ICHRA plan year or the date it ends, and confirm when the last allowance is paid.
- Tell employees early Use a planning target of at least 30 days, but have the administrator check all required notices and contract deadlines. After confirming replacement enrollment, employees who want to avoid overlapping coverage should cancel their own individual policies, effective the day before the group plan starts, so nobody pays for two plans.
- Watch the Thatch Card balance Ask Thatch what happens to unspent Card funds when the ICHRA ends and tell employees the deadline to use them.
- Enroll and set deductions Run enrollment for the group plan and set up payroll deductions for any employee share. Employees who keep their individual plan should know they lose the allowance.
For timing details, see switching health insurance mid-year and should we switch from a group plan to ICHRA?
The group plan alternative
For employers choosing group coverage, at Prescience we design and run your company's group health plan, from setup and enrollment to claims, compliance and COBRA. What your team gets:
- An effective $0 deductible, so the plan helps from the first visit.
- Simple copays shown before a visit, capped by a low out-of-pocket maximum.
- A broad national PPO network, plus providers we contract with directly.
- 24/7 physician-led care navigation: a care team that finds the right provider, books appointments and explains costs up front.
What your company gets: one monthly cost set in your quote, usually 10–20% below comparable fully insured coverage and fixed before the plan starts, with no admin fees. You keep your payroll provider, and the plan can start mid-year.
Check what the budget promises
I would distinguish three amounts in the proposal: the maximum employer allowance, the amount actually reimbursed and the platform fee. They need not be equal. Ask when funds become available, whether unused amounts carry over and what happens when an employee leaves or changes coverage. If the employer allows expenses beyond premiums, obtain the eligible-expense rules and claim deadline. A card balance is not a bank account owned by the employee.
For an affordable ICHRA offer, declining the benefit does not by itself restore premium tax credits. For an unaffordable offer, the employee must opt out and otherwise qualify for credits. Use the lowest-cost silver self-only premium for the applicable affordability calculation, not the second-lowest-cost benchmark used to calculate Marketplace credits. Employer safe harbors do not replace the employee’s household-income analysis.
Before launch, ask the administrator to confirm permitted classes, any minimum class size, and notices. Generally the notice is due 90 days before the plan year; newly eligible employees and newly established employers have special timing. The special enrollment period associated with an ICHRA is tied to when coverage can begin and the applicable notice rules, so employees should confirm their personal deadline. Keep the old policy until the replacement enrollment and effective date are confirmed.
See what your team would pay with Prescience
Answer a few questions about your team and get a quote in about 60 seconds, or talk it through with one of our benefits experts.